

US Nonfarm Payrolls October 2026: Jobs Rebound?
US Nonfarm Payrolls October 2026: Will the Jobs Market Finally Rebound?
The US jobs report drops today, and after September's ugly miss, markets are not taking any chances. The US nonfarm payrolls October 2026 figure lands at 13:30 UTC, with economists pencilling in around 65,000 new jobs. That would be more than double September's 29,000 print, though still nothing close to what a healthy labour market normally delivers. With the Federal Reserve's December meeting just over a month away, today's number carries more weight than usual.
The setup is tense. Job creation has been patchy all year, government data was disrupted by the shutdown earlier in 2026, and the Fed is sitting on the fence about its next move. One strong print does not fix all of that, but one more weak one could push rate cut expectations sharply higher. Traders know this, and positions are being held tight ahead of the release.
September's Miss Set a Low Bar
Last month's jobs report landed well below expectations. The US economy added just 29,000 jobs in September against a consensus of 89,000. That was not a rounding error. The unemployment rate also ticked up to 4.2%, wage growth slowed to 3.0% year-on-year, and the previous month's figure was revised lower. According to the Bureau of Labor Statistics, it was one of the softest readings of the year.
What made September harder to dismiss was the breadth of the miss. It was not concentrated in one sector. Private payrolls were soft across the board, and the rise in unemployment was partly driven by more people returning to look for work without finding it quickly enough. That is a different story from a labour market that simply paused. It suggests hiring has genuinely cooled.
Markets reacted accordingly. The dollar fell, gold climbed back above the 4,180 level, and Treasury yields dropped as traders raised the probability of a Fed pivot. That repricing has been slowly unwinding since then, which is part of why today's US nonfarm payrolls October 2026 report matters so much. The market is looking for confirmation that September was an outlier, not a signal.
What the Data Going In Looks Like
Two early reads on October employment came in better than feared. ADP's private payrolls report, released on November 4, showed 86,000 jobs added against a forecast of 67,000. That beat gave markets some reason to expect a recovery in the official figure, though ADP and BLS data do not always line up cleanly.
Initial jobless claims have also stayed contained. The most recent reading came in at 194,000, below the forecast of 198,000. Claims at that level are not consistent with a labour market that is falling apart. They suggest companies are not cutting staff aggressively, even if they are not hiring at the pace seen in 2024 or early 2025.
The consensus for today sits at around 65,000 payrolls, with unemployment expected to hold at 4.1%. But the range of estimates is wide. Some forecasters see as few as 40,000, others closer to 100,000. That spread reflects genuine uncertainty about where the economy actually stands, and it means the market reaction to the actual print could be sharp in either direction.
What a Strong Number Does to Markets
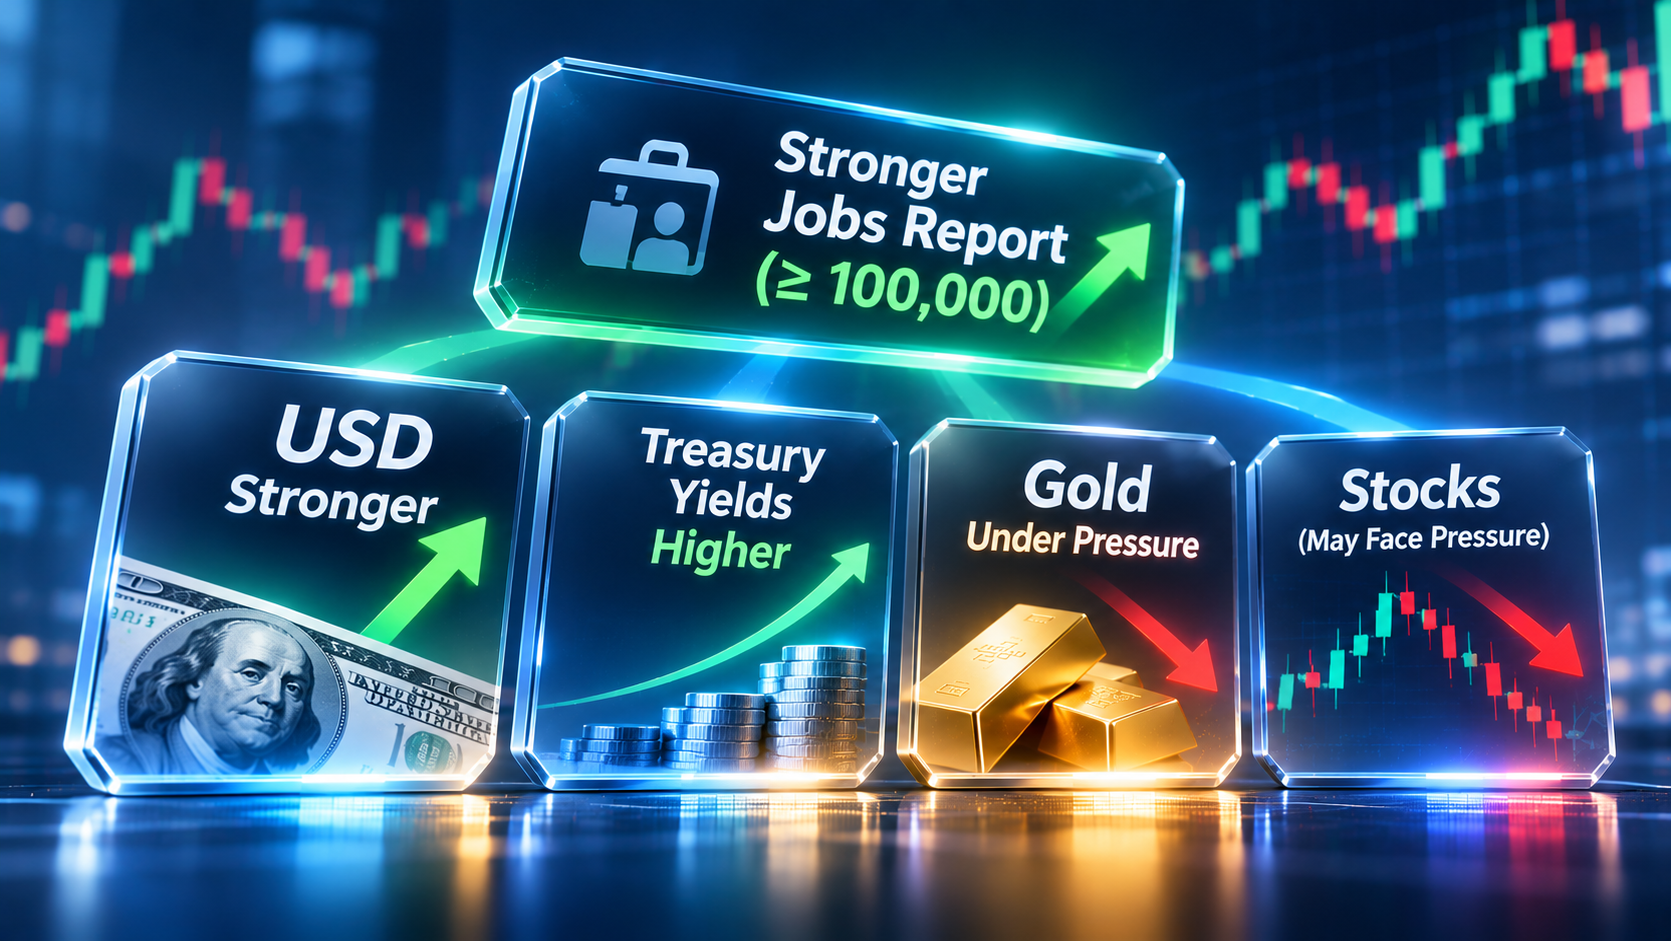
If October payrolls come in at 100,000 or above, the dollar is the immediate beneficiary. A strong beat would signal that September was a one-off and that the labour market is holding up well enough to keep the Fed on hold in December. Treasury yields would likely move higher, the dollar index could recover toward 102.00 from its current level near 101.60, and rate cut expectations would be pushed further into 2027.
Gold would face pressure in that scenario. US nonfarm payrolls October 2026 data that beats expectations tends to lift the dollar and yields, both of which work against gold. The metal has been trading near 4,186 ahead of the release, and a strong jobs print could drag it back toward the 4,000 support zone, particularly if wage growth also comes in above 3.5% year-on-year.
Equity markets are a more complicated picture. Strong jobs data is not automatically good for stocks when rates are already elevated. If the jobs number reignites fears that the Fed will stay higher for longer, tech and growth stocks in particular could sell off even as the dollar rallies. That tension between good economic news and higher rate expectations has been a recurring theme throughout 2026.
What a Weak Number Changes
A miss today would reopen the December cut conversation fast. If October payrolls come in below 40,000, or if the unemployment rate climbs to 4.3% or higher, the market would likely move quickly to price in a rate cut at the December 9 FOMC meeting. That scenario would push the dollar lower, lift gold, and flatten the yield curve as short-term rate expectations fell.
Gold bulls have been patient. The metal has held above 4,000 for most of 2026, supported by central bank demand, geopolitical uncertainty, and rising concerns about US fiscal sustainability. A weak US nonfarm payrolls October 2026 print would add a macro tailwind on top of those structural supports, and 4,250 becomes a realistic near-term target if the miss is significant.
Beyond the headline, revisions to September's figure matter too. If BLS revises that 29,000 print lower, it compounds the signal. If it revises it higher, it softens the narrative and reduces the urgency for the Fed to act in December. Markets will be watching the revision line just as closely as the October number itself, since back-to-back weak prints tell a different story than one isolated miss.
The Fed's Position Going In
The Federal Reserve has been careful not to commit in either direction. Rate hike odds hover near 20% for December, meaning the base case is a hold. But a hold is not a fixed outcome. It is the market's best guess given the data available today, and today's data could shift that calculation.
What the Fed wants to see is a labour market that is cooling gradually without cracking. A slow softening in job creation, combined with inflation trending lower, is the soft landing scenario. September looked more like a crack than a cooling. October needs to show that the floor is still holding.
Fed officials have consistently said they are data-dependent. Today is a genuine test of that. The October US nonfarm payrolls report and the November 10 CPI release are the two most important inputs before the December 9 decision. A jobs miss combined with a soft CPI would almost certainly lock in a December cut. A jobs beat combined with sticky CPI would push any cut well into 2027. Everything else is noise by comparison.
The Year in Context
It helps to step back and look at the full 2026 picture. This has not been a straight line in either direction. February saw payrolls drop 92,000, one of the worst prints in years. March bounced back to 178,000. July fell again to -23,000. August recovered to 162,000. Then September came in at 29,000.
That volatility has made it genuinely hard to read where the trend sits. The monthly swings have been larger than normal, partly because of the government shutdown's effect on data collection and reporting, and partly because the underlying economy has been sending mixed signals. Consumer spending has held up better than expected. Business investment has been more cautious. The labour market sits somewhere in between.
What we can say with reasonable confidence is that job growth has slowed from the pace of late 2024. The question is whether it has slowed to a sustainable crawl or whether it is heading for something worse. Today's US nonfarm payrolls October 2026 release will not fully answer that question, but it will narrow the range of plausible outcomes considerably.
Key Levels for Traders to Watch
Going into the 13:30 UTC release, here are the ranges that matter across asset classes:
- NFP above 100,000: Dollar rally, gold under pressure, yields higher, equities mixed on rate fears
- NFP between 60,000 and 100,000: In-line result, limited directional move, focus shifts to wages and unemployment rate details
- NFP below 40,000: Dollar selloff, gold supported, rate cut expectations spike, equities weaker on growth concerns
EUR/USD has been consolidating near 1.1163, with resistance at 1.1223. A weak jobs report could push it toward that level. USD/JPY holds near 157.49, and a soft number would likely pull it back toward 155.00 as yen demand increases. The 10-year Treasury yield, currently near 5.1%, is the clearest gauge of how the market is interpreting the Fed implications of whatever comes out.
Watch the Details, Not Just the Headline
The first number that hits the wire will move markets. But experienced traders know the full picture takes a few minutes to emerge. Beyond the headline payrolls figure, three things deserve attention: the revision to September's 29,000, average hourly earnings on a month-on-month and year-on-year basis, and the labour force participation rate.
Wages above 3.5% year-on-year would signal lingering inflation pressure and reduce the case for rate cuts even if the headline payrolls miss. Participation ticking higher while unemployment rises would be a negative signal about the quality of job demand. A downward revision to September would add to concerns about trend deterioration.
If wages come in strong but payrolls disappoint, the market faces a conflicted signal: the labour market is not growing fast, but it is still generating wage pressure. That combination is the hardest one for the Fed to navigate and would likely produce choppy, two-way price action rather than a clean directional move.
Release time: Friday, November 6, 2026 at 13:30 UTC (8:30 AM ET). Watch USD pairs, gold, and US equity futures in the minutes following for the initial directional read. According to Investing.com, gold is currently trading near 4,186 and the dollar index sits at 101.60 ahead of the release. The US nonfarm payrolls October 2026 figure will not resolve everything that is unclear about this economy, but it will give markets a clearer read on whether the Fed has room to pivot, hold, or push back. That question is worth watching closely today.
FAQ
Frequently asked questions
What time does the October 2026 NFP report come out? +
The US nonfarm payrolls October 2026 report is released on Friday, November 6, 2026 at 13:30 UTC (8:30 AM ET, 9:30 PM MYT). USD pairs, gold, and US equity futures are the primary instruments to watch in the minutes following the release.
What is the forecast for October 2026 nonfarm payrolls? +
The consensus forecast for October 2026 nonfarm payrolls is approximately 65,000 jobs, more than double September's 29,000 print. The range of estimates runs from around 40,000 to 100,000, reflecting genuine uncertainty about the labour market's current trend.
How will the NFP report affect the Fed's December decision? +
A strong NFP print above 100,000 would reduce the case for a December rate cut and push rate cut expectations further into 2027. A weak print below 40,000 would likely reignite the December cut conversation and shift market pricing sharply toward a Fed pivot.
What does a weak NFP number mean for gold? +
A weak US nonfarm payrolls October 2026 result would add a macro tailwind to gold's existing structural supports. If payrolls miss significantly, rate cut expectations would rise, the dollar would soften, and gold could move toward 4,250 as a near-term target.
What details should traders watch beyond the headline NFP number? +
Three things deserve attention beyond the headline: the revision to September's 29,000 print, average hourly earnings on a month-on-month and year-on-year basis, and the labour force participation rate. Wages above 3.5% year-on-year would signal lingering inflation pressure and reduce the case for rate cuts even if the headline payrolls miss.
Trade the markets you follow
Open a live or demo account in minutes
KVB Market Analysis
Latest from our insights